Starting a business from zero is hard for anyone, but it is even harder when banks hesitate to lend simply because you belong to a community that has historically had less access to formal credit. The Stand-Up India Scheme was created to close exactly this gap. It is a Government of India initiative that pushes every scheduled commercial bank branch to sanction loans between ₹10 lakh and ₹1 crore to at least one Scheduled Caste (SC)/Scheduled Tribe (ST) borrower and one woman borrower, so they can set up a brand-new (“greenfield”) business.
What Is the Stand-Up India Scheme?
The Stand Up India Scheme provides bank loans between ₹10 lakh and ₹1 crore to at least one Scheduled Caste (SC) or Scheduled Tribe (ST) borrower and at least one woman borrower per bank branch, for setting up a greenfield project. The scheme was launched by Prime Minister Narendra Modi in April 2016 to support women and SC/ST entrepreneurs in India.
In simple words: the government has told banks that they cannot ignore first-time SC/ST and women entrepreneurs. Every branch has a lending target for this group every year, backed by a dedicated online portal, handholding support, and a credit guarantee cover so banks feel safer lending without heavy collateral.
Why “Greenfield” Matters
“Greenfield” means the enterprise must be a first-time venture — not an expansion, renovation, or takeover of an existing business. The scheme exists to help people start something new, not to refinance or scale something that already exists.
Ministry and Implementing Agency
The scheme is coordinated by the Department of Financial Services (DFS), Ministry of Finance, with SIDBI (Small Industries Development Bank of India) and NABARD providing operational and refinance support through the Stand-Up Mitra portal.
Key Features at a Glance
| Feature | Details |
|---|---|
| Loan Amount | ₹10 lakh to ₹1 crore |
| Loan Type | Composite loan (term loan + working capital in one facility) |
| Eligible Sectors | Manufacturing, services, trading, agri-allied activities |
| Project Type | Only greenfield (new) enterprises |
| Margin Money | Around 25% of project cost (can be part-funded via convergence with other government schemes) |
| Repayment Tenure | Up to 7 years |
| Moratorium Period | Up to 18 months |
| Collateral | Often reduced or waived through credit guarantee cover |
| Portal | standupmitra.in |
| Launch Year | 2016 |
Eligibility Criteria
Eligibility is where most confusion happens, so let’s separate it clearly.
For SC/ST Entrepreneurs
- Must belong to a recognised Scheduled Caste or Scheduled Tribe, supported by a valid caste certificate.
- Age must be 18 years or above; there is no upper age limit specified.
- Must hold at least 51% shareholding and controlling stake in the enterprise (in case of a company or partnership).
For Women Entrepreneurs
- Any woman aged 18 years or above.
- No caste/category restriction — open to all women.
- Must hold at least 51% ownership and controlling stake in the business.
General Conditions (Apply to Everyone)
- The applicant must not be an existing defaulter with any bank or financial institution.
- The project must be a new (greenfield) venture — not an existing or expanded business.
- The business can be a sole proprietorship, partnership, or a company where the eligible person holds majority control.
- Preference is generally given to applicants who take support from a Stand-Up Connect Centre (SUCC) or a registered mentor for preparing the project report.
Loan Amount, Purpose, and Composite Structure
Loan Slabs
| Loan Component | Minimum | Maximum | Typical Use |
|---|---|---|---|
| Term Loan | Part of ₹10 lakh | Part of ₹1 crore | Machinery, equipment, infrastructure |
| Working Capital | Part of ₹10 lakh | Part of ₹1 crore | Raw material, salaries, day-to-day expenses |
| Composite Loan (Total) | ₹10,00,000 | ₹1,00,00,000 | Combined funding under one facility |
Banks in Stand-Up India offer business loans ranging from ₹10 lakh to ₹1 crore, meant specifically for greenfield enterprises in manufacturing, services, or trading sectors.
What the Loan Can Be Used For
- Purchase of machinery, tools, or equipment
- Setting up a manufacturing unit, workshop, or service outlet
- Working capital such as raw materials, inventory, and wages
- Trading and distribution setup
- Agri-allied ventures such as poultry, dairy processing, or food processing units
Interest Rate and Margin Money
The interest rate under Stand-Up India is decided by individual banks and usually ranges between 8% and 12% per annum, depending on the borrower’s credit profile, the bank’s internal policy, and prevailing repo-linked lending rates. Margin money requirement is generally only 25%, and this portion can be met through convergence with other central or state government schemes, reducing the upfront cash burden on the entrepreneur.
Credit Guarantee Support
The Credit Guarantee Fund Scheme for Stand-Up India (CGFSIL) covers bank risk, which reduces collateral requirements and improves approval chances for applicants who may not otherwise have significant assets to pledge.
Repayment and Moratorium
- Repayment Tenure: Up to 7 years
- Moratorium Period: Up to 18 months before EMI payments begin, giving the business time to stabilise before repayment starts
How to Apply: Step-by-Step Process
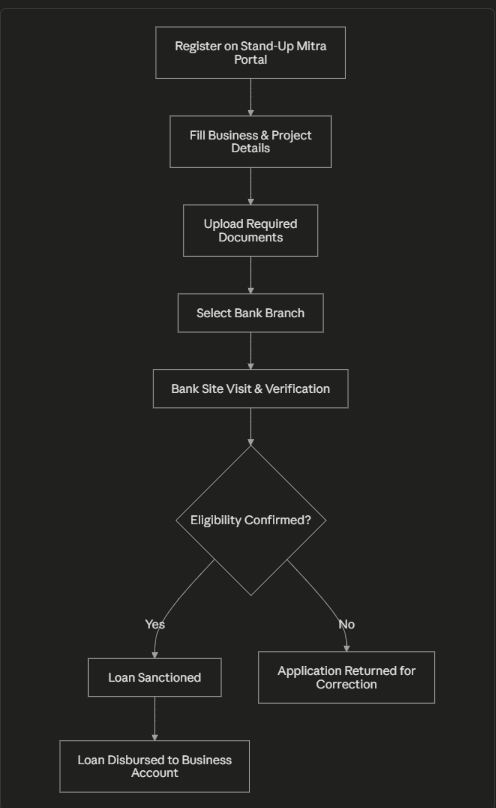
Step 1: Visit the official Stand-Up India portal. Step 2: Register as a new user or log in if you already have an account, using your name, email ID, and mobile number. Step 3: Generate an OTP and fill in the application form with details such as business type, ownership pattern, project cost, and proposed activity. Step 4: Upload the required documents; the portal checks whether the uploaded files meet the eligibility criteria. Step 5: Select a bank branch from the list of participating branches. Step 6: Review all details carefully and submit the application online. Step 7: The bank verifies the details, checks eligibility, and — once approved — disburses the loan to the business account.
Alternative Offline Route
You can also walk into any public sector, private sector, or regional rural bank (RRB) branch and directly ask for a “Stand-Up India loan,” carrying your project report and documents. The branch manager will guide you through a pre-sanction site visit before final approval.
Application Flow Diagram
flowchart TD
Documents Required
| Document Type | Examples |
|---|---|
| Identity Proof | Aadhaar Card, PAN Card, Voter ID |
| Category Proof | Valid SC/ST Caste Certificate (issued by Tehsildar/SDM, not lower authorities) |
| Address Proof | Utility bill, ration card, or Aadhaar |
| Business Proof | Project report, business plan, quotations for machinery |
| Financial Documents | Bank statements (last 6–12 months), IT returns if applicable |
| Photographs | Recent passport-size photographs |
| Ownership Proof | Partnership deed / MoA-AoA (if applicable), showing 51% controlling stake |
Key Benefits of the Scheme
- Access to a sizeable loan (up to ₹1 crore) without requiring an established credit history
- Reduced collateral burden through government credit guarantee cover
- Composite loan structure so you don’t need to apply separately for working capital and term loans
- Handholding support through SUCC mentors and SIDBI-linked resources for preparing project reports
- Long repayment tenure and moratorium, giving new businesses breathing room before EMIs start
- Encourages local employment generation since every branch is mandated to lend to this segment annually
Stand-Up India vs Other Government Loan Schemes
| Parameter | Stand-Up India | PM Mudra Yojana | PMEGP |
|---|---|---|---|
| Loan Range | ₹10 lakh – ₹1 crore | Up to ₹20 lakh | Up to ₹50 lakh (manufacturing) / ₹20 lakh (service) |
| Target Group | SC/ST & Women (greenfield only) | Any small business owner | Any first-time entrepreneur |
| Subsidy | No direct subsidy; margin money convergence allowed | No subsidy | Government subsidy of 15–35% |
| Collateral | Reduced via CGFSIL | Not required (collateral-free) | Reduced via credit guarantee |
| Ideal For | Mid-sized new ventures | Micro and small businesses | Manufacturing/service units with subsidy need |
Stand-Up India loans range between ₹10 lakh and ₹1 crore, while Mudra covers up to ₹20 lakh; these two schemes are not meant to be combined for the same project.
Common Mistakes That Lead to Rejection
- Submitting a vague or generic project report instead of one tailored to your specific business — get help from an SHG, NGO, or a chartered accountant if needed
- Applying for an existing business in the same line of activity — remember, greenfield strictly means new
- Not arranging the margin money (own contribution) in advance — banks will not disburse without proof of it
- Submitting a caste certificate from an unauthorised authority (like a Patwari) instead of a Tehsildar or SDM
- Structuring joint ownership incorrectly — the eligible SC/ST or woman applicant must hold at least 51% stake, not less
Frequently Asked Questions
What is the loan amount under the Stand-Up India Scheme?
The scheme offers loans from ₹10 lakh to ₹1 crore to eligible SC, ST, and women entrepreneurs for starting a new business.
Who is eligible for the Stand-Up India Scheme?
SC, ST, and women entrepreneurs above 18 years of age, starting a new business with at least 51% ownership, are eligible.
What is the interest rate under this scheme?
The interest rate is decided by individual banks and usually ranges between 8% and 12% per annum.
How can I apply for the Stand-Up India Scheme online?
You can apply online through the Stand-Up Mitra Portal by registering and submitting your business and personal details.
Is collateral mandatory for a Stand-Up India loan?
Collateral may be required in some cases, but many loans are covered under a government credit guarantee scheme, which reduces this requirement.
Can I use both Stand-Up India and Mudra Yojana for the same business?
No — Stand-Up India and Mudra Yojana cannot be combined for the same project; you must choose one scheme per business venture.
Is there an age limit for applicants?
The minimum age is 18 years, and there is no upper age limit specified.
Important Note
This article is for general informational purposes. Loan approval, interest rates, and final terms are entirely at the discretion of the lending bank and subject to change by the Government of India. Always verify the latest guidelines on the official portal before applying.
Quick Links
| Resource | Link |
|---|---|
| Application Form | Click Here |
| Official Site | Click Here |
| Other Sarkari Yojana Info | Click Here |
| Credit Guarantee Scheme Details | Click Here |
| Home Page | Click Here |